The government has announced a new scheme designed to help more first time buyers take their first step onto the property ladder, with a deposit of just 2.5%.

Confirmed in the Autumn Budget, the Your First Home scheme will offer eligible buyers a government-backed 20% equity loan to help them purchase a new-build home, reducing the amount they need to save for a deposit and borrow through a mortgage.

For many aspiring buyers, the announcement will be exciting news, potentially bringing their homeownership dreams within reach. To help you understand how the scheme could work for you, we’ve broken down how it will work, who will be eligible and when can you apply.
What is the Your First Home scheme?

Your First Home is a new government-backed scheme designed to make homeownership more accessible for first-time buyers in England, particularly those who may struggle to save for a large deposit.

Under the scheme, eligible buyers will be able to purchase a new-build property with a deposit of just 2.5% of the purchase price, alongside a government equity loan worth 20% of the property’s value.

How much deposit will I need?

One of the biggest benefits of the scheme is the reduced deposit requirement, which could make a significant difference for those struggling to build up their savings. For example, if you’re looking to purchase a £300,000 home, the costs could look like this:

  • Your deposit (2.5%): £7,500
  • Government equity loan (20%): £60,000
  • Your mortgage (77.5%): £232,500

Without the scheme, purchasing the same property with a 95% mortgage would typically require a £15,000 deposit and a £285,000 mortgage.

While the equity loan will be interest-free for the first five years, interest will apply from year six, starting at 1.5% and increasing to 3% from year seven. Buyers will also need to repay the equity loan itself, so it’s important to consider these future costs when planning your purchase.

Who is eligible for Your First Home?

The scheme will be available to eligible first-time buyers purchasing a new-build home in England. To qualify, buyers will generally need to:

  • Be a first time buyer purchasing a home to live in as their main residence.
  • Have a household income of no more than £140,000 in London or £110,000 outside London.
  • Purchase an eligible new-build property from a participating developer or housing association
  • Meet the affordability and lending requirements of a participating mortgage provider.

Property price caps will also apply, depending on the location of the home. In London, these will be set at £650,000 for inner London, £500,000 for outer London and £355,000 for Manchester, with different limits applying across the rest of England.

Further details on eligibility and local property price caps will be published ahead of the scheme’s launch.

How is Your First Home different from Shared Ownership?

Both Your First Home and Shared Ownership are designed to help make buying a home more accessible, but they work in different ways.

With Your First Home, buyers purchase their property outright using a mortgage, their own deposit and a government equity loan, which must be repaid.

Shared Ownership, meanwhile, allows eligible buyers to purchase a share of a property, usually between 10% and 75%, while paying rent on the remaining share. Buyers can then increase their ownership over time through a process called staircasing.

Both schemes offer different routes onto the property ladder, giving aspiring homeowners more options depending on their individual circumstances and financial goals.

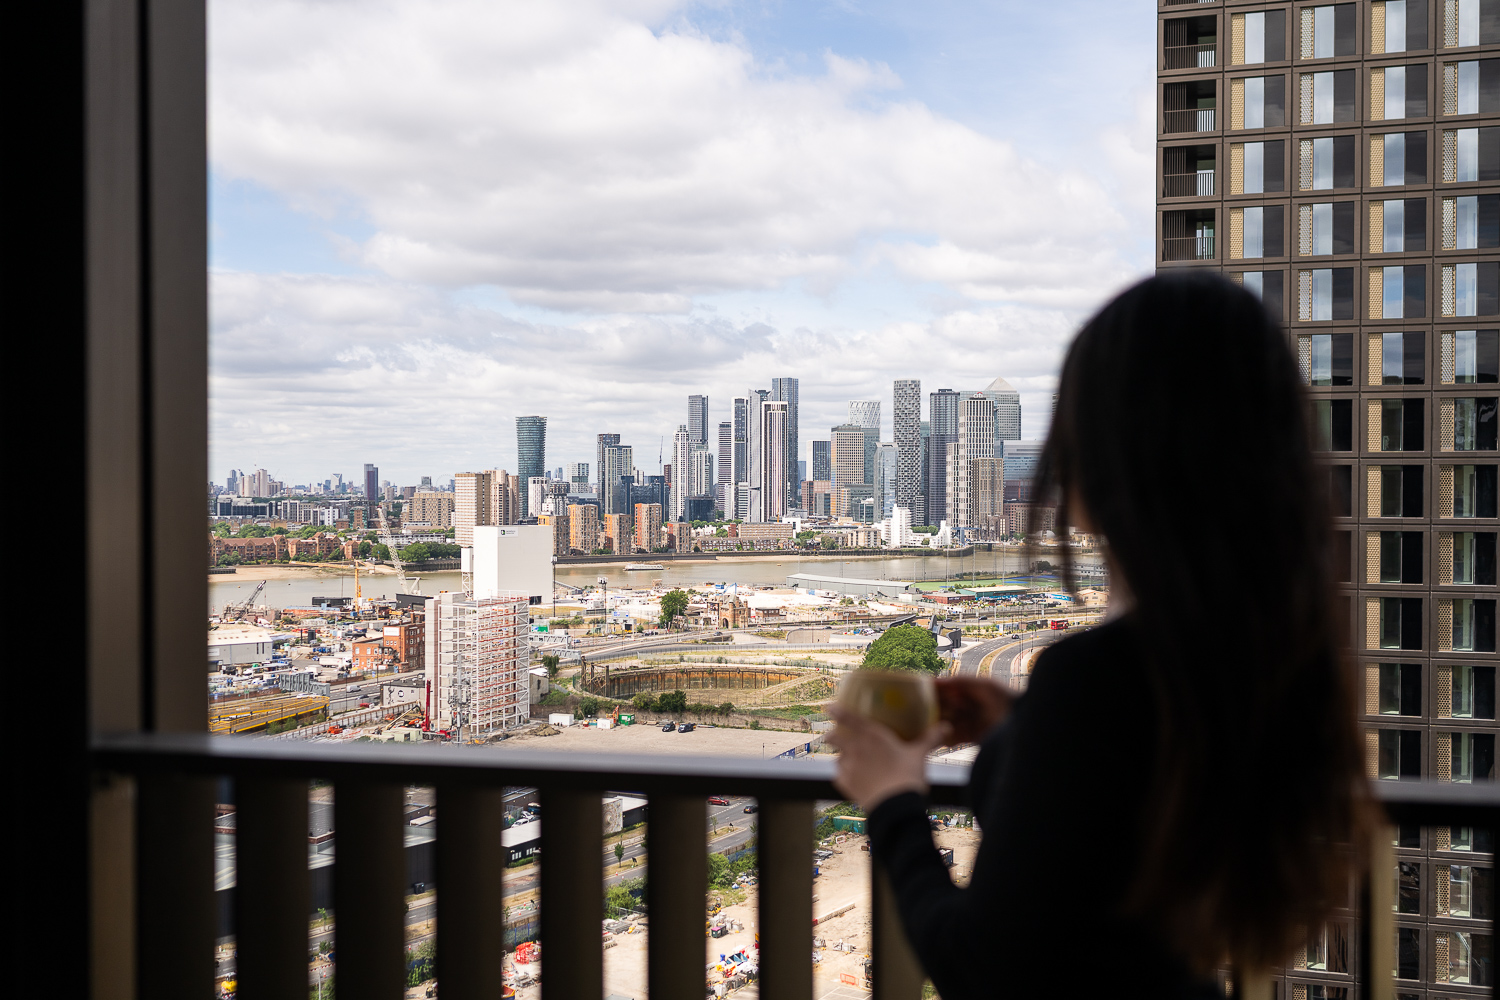
Shu Ming looking at stunning view of London from Prime Point

When will the Your First Home scheme launch?

The scheme will open for applications in February 2027, with the first property sales anticipated from April 2027. Pre-registration is expected to open before the end of 2026, allowing prospective buyers to find out more about their eligibility and the property price limits in their area.

Further information about participating developers, lenders and available properties will be announced ahead of the launch.

Kew Bridge Rise living room with warm lighting

In the meantime, if you're considering taking your first step onto the property ladder, why not explore the range of homes and homebuying options currently available with L&Q

You can also find out more about the Your First Home scheme on the government’s website.

The information provided is based on government guidance available at the time of publication (29th October 2026), as outlined here. Scheme details, including eligibility criteria, interest rates and property price caps, may be subject to change. Buyers should refer to the latest government guidance and seek independent financial advice before making any financial commitments.